冠君產業信託(02778)行政總裁及投資總監王家琦表示,放售旗下朗豪坊辦公樓一事,代理本周剛開始在內地路演尋找買家,尚未成事,若落實出售,變現後或有更好的再投資機會,繼續以香港項目為優先,可整幢大廈收購、自行發展或與人合資;若未有合適的投資機會,便可能派發特别息;所得資金不會用作償還債務,因效益不高。
王家琦説,旗下三項資產之中,花園道三號價值逾千億元,難覓買家;而朗豪坊商場則是上任行政總裁李澄明及主席羅嘉瑞辛苦經營多年所建立的品牌,不想出售;冠君見市道暢旺,自己買不到合適資產,便索性轉做賣家,出售朗豪坊辦公樓,按高賣低買原則,待某個周期時段再出手收購。
她笑稱,作價250億元是代理心目中的意向價,希望得到理想回報,若市場出價不合意,不會盲目出售,朗豪坊辦公樓的收入仍有機會繼續上升。
王家琦指出,花園道三號的平均租金仍較市價低很多,租金水平續有上升空間,會是主要動力。朗豪坊商場受電梯事故影響下,業務表現仍跑贏大市,底租及分成租金收入均有不錯升幅;由於分成租金比率約20%,對底租租金構成壓力,但不表示底租會大跌;7月及8月至今人流好,按年有升幅。
2017年8月15日星期二

2017年5月10日星期三
爆升的冠君產業信託(2778.HK)

筆者組合中的冠君產業信託(2778.HK)由年初的HK$4.21到今天收$5.21,短短5個月升了23%!!與同期其他的reits比較:領展(823) +11%⬆;置富(778) +1.5%⬆;越秀(405) +12%⬆;升幅可謂驚人。特別是這幾天港股升市中,其他reits牛皮或下跌,冠君可算突出,且屢創新高。
市場上都在估算後天截標的中環花園道舊停車場做價若干,預計投標者眾,成交極可能是天價。
筆者好奇,翻查冠君2016年報,看看持有的花園道3號帳面估價多少。此物業共163萬平方呎,估值393億,即平均約$24000/呎。筆者大膽估算後天的成交樓面地價約$35000至40000/呎,項目完成計入成本每呎將超過$45000/呎。現價冠軍的PB值只是0.59,帳面折讓之高已經是香港眾reits之冠。如果計入新價,粗略估值將增加340億,PB將會降低至約0.38!
筆者多疑,咁筍?如果有錢一定全面收購,然後拆骨,一定賺到笑😆😆!咁簡單的思維,冇理由大股東唔知?立即去etnet看看最近冠君的股權變化如何。
鷹君和羅生是冠軍的大股東,由2016年3月開始,幾乎每個月都靜靜吸入冠君股份,持股量由62.91%增持至今年4月27日66%,即約一億八仟萬股,平均每月1400萬股😎。筆者相信香港第一隻有可能私有化的reits應該非冠君莫屬。雖然大股東的耐性有幾長不知道,但身為小股民的筆者能夠以大折讓持有優質核心物業,收住息來等,應該是不錯的選擇。
(溫馨提示:此文章乃筆者即興之作,數據也沒經詳細考核,非對讀者投資建議,純粹遊戲文章自娛。且市場上常常出現估對了卻輸錢的例子。說不定出現反高潮,成交真的出現天價,卻是好消息出貨都唔出奇。慎之!)
2017年4月10日星期一
專門投資Data Centre的Keppel DC Reits

筆者發現這隻新加坡上市的Keppel DC Reits (AJBU)幾特別,是亞太區第一隻專注投資於Data Centre(數據中心)的房地產投資信託基金。它的領域包括主機託管,設施齊全的周邊和核心裝置。公司13個data centre均位中心樞紐。如Gore Hill Data Centre,S25;T25;Citadel100 Data Centre;iseek Data Centre;GV7 Data Centre,Basis Bay和Almere Data Centre。資產主要位於澳洲,英國,德國,意大利,馬來西亞,新加坡和愛爾蘭。
作為分散行業及地域風險,除了主流的商場、寫字樓、酒店、工業,物流、醫療reits外,數據中心也算是擁有穩定收益的選擇!現息率約5%,預計息率6.1%。現價SGD$1.22
詳細資料請參閱Keppel公司網址連結
以下是OCBC的研究報告:
OCBC Investment Research has reiterated a ‘Buy’ rating on Singapore-listed Keppel DC REIT, citing growth potential in the demand for data centre properties.
This demand is underpinned by expected increases in data creation, and outsourcing, said the bank in an investment report on 3 April.
Citing figures from information consulting company BroadGroup, OCBC noted that this demand is expected to grow at a compound annual growth rate (CAGR) of between 4.7% to 14.7% in key cities that Keppel DC REIT is exposed to from 2016 to 2021.
In addition, OCBC also looks upon favourable on Keppel DC REIT’s weighted average lease expiry (WALE) of 6.9 years, making it one of the most defensive REITs in Singapore, the firm opined.
“Based on our forecasts, [Keppel DC REIT] is offering distribution yields of 6.1% and 6.3% for FY17F and FY18F, which is attractive relative to its peers’ Bloomberg consensus average yield of 3.8% and 4.1%, respectively”, said OCBC.
The bank has maintained a fair value estimate of SGD1.39 on the data centre REIT.
2017年3月1日星期三
My updated reits組合(2017年3月)


經過半年的調整,除了日本的組合逆市下跌較大令人失望外😐,香港和新加坡的reits也相對穩定。整個組合價值跌了約6%。大市升,reits卻跌,少不免影響了心情。但收息情況令人滿意,如果不介意短期價格波動,也算達到收息預期。這段時間,筆者減低了新加坡reits的數目至9只,減持太集中於新加坡商場和office的reits。香港的reits也只有3只。日本的reits亦減持至4隻。預算整個組合半年後才會再re-adjust!也預留了資金空間在大跌市時(若有)增持部份reits,務求升市時有貨在手,坐收穩定現金流入,跌市時有錢買貨,這樣就能升跌皆樂。去蕪存菁後,省了要關心的打理時間!整個組合的派息率約5.5%,計入槓干扣除借貸利息,年派息大約是本金的10%!這也是我預期的目標!😄
2016年8月9日星期二
9 things learned from Mapletree Commercial Trust’s 2016 EGM
By Adam Wong on August 2, 2016
文章連結


文章連結
On 5 July 2016, Mapletree Commercial Trust (SGX: N2IU) (MCT) announced a proposed acquisition of an office and business park property, Mapletree Business City (MBC), for a purchase consideration of $1.78 billion. This will be MCT’s second acquisition since its IPO.
As a unitholder myself, I attended the extraordinary general meeting MCT held immediately after itsFY2016 AGM to find out more details about the proposed acquisition and to vote on the proposed resolutions.
Here are 9 things I learned from Mapletree Commercial Trust’s 2016 EGM:
1. MCT is acquiring Phase 1 of MBC
MCT is acquiring Phase 1 of MBC which comprises an office tower and three business park blocks. Phase 1 was completed in April 2010 while Phase 2 of MBC is currently under development and is due for completion this year. The leasehold for MBC (Phase 1) is 80 years till 2096.
2. Total acquisition cost is $1.86 billion
The purchase consideration is $1.78 billion which is a 2.3% and 2.8% discount to DTZ’s and Knight Frank’s independent valuation of MBC respectively. The total acquisition cost, however, is $1.86 billion after including acquisition fees paid to the manager ($8.9 million paid in units), stamp duty to the government ($53.4 million), and estimated professional fees and expenses ($16.2 million).
3. Acquisition is NAV and DPU accretive
The acquisition is expected to be accretive for net property income (NPI) yield, NAV, and distribution per unit (DPU). NPI yield will increase from 5.1% to 5.2%. NAV per share will increase to $1.31 and DPU will rise from 4.14 cents to 4.27 cents.
4. Exposure to the Alexandra/HabourFront office market
The management views MBC as a strategic addition to its portfolio. The property is of the largest integrated office and business park complexes in Singapore. It is located 10 minutes from the central business district (CBD) and directly connected to Labrador Park MRT station.
It attracts tenants who wish to be located near the CBD without having to pay sky-high rents. The Alexandra/HabourFront area offers rents which are 28.8% and 8.5% lower than Grade-A and Grade-B Core CBD offices respectively. Average office rent at MBC is $6.14 per square foot per month.
Historically, prime office rents in Alexandra/HabourFront are also less volatile resilient than Grade-A and Grade-B Core CBD office rents.
5. Exposure to growing business park segment
Mapletree Business City is the closest business park to the CBD and the growing demand for business parks is evident in MNCs like Google, American Express, HSBC, Nike, SAP, Samsung and Unilever relocating from the CBD to MBC.
Singapore business park rents are also extremely stable compared to office rents and there is no new business park supply expected until 2020. Average business park rent at MBC is $5.88 per square foot.
6. Committed occupancy rate is at 99.0%
MBC is a large property with a total net lettable area (NLA) of 1,708,218 square feet comprising 420,544 square feet in offices and 1,287,674 square feet in the business park. Even so, occupancy levels as at 30 April 2016 is 97.8%, while the committed occupancy rate is 99.0%. Weighted average lease expiry is 3.5 years and 97.5% of leases have average annual rental step-ups of around 3%.
7. Acquisition to be financed by a combination of debt and equity
MBC’s total acquisition cost of S$1.86 billion will be funded by loan facilities of up to $920 million and an issue of up to 795 million new units via a private placement to institutional investors and preferential offering to existing unitholders.
8. Some unitholders had questions and concerns
One unitholder felt that the acquisition was not in the interest of minority unitholders. He agreed that MBC was a good asset but thought that the acquisition price was too high and, as a result, the DPU accretion too low. He questioned why the management had to make the acquisition at this point in time when the office sector is soft and suggested that the deal might be better suited when the office sector improves.
Chairman Tsang Yam Pui expressed surprise at the unitholder’s view as many investors have long asked when MBC would be acquired by MCT. Tsang explained that an asset of MBC’s quality is hard to find and would be very expensive in the open market. The fact that MCT is able to acquire the property at a price that allows for DPU and NAV accretion is a positive for unitholders. The property would also give good organic growth in the long run. The chairman also said that a good time to acquire a good asset is when you can get it at the right price. In the case of MBC, MCT is already acquiring it a discount to the valuation set by two independent valuers.
Another unitholder asked if the supply of nearby office properties like Alexandra Technopark and Fragrance Building (formerly NOL Building) would affect MBC. CEO Sharon Lim replied that in the next four years, only 4% of office leases at MBC are expiring in FY2018/19. Furthermore, the quality of an asset like MBC is a world of difference compared to the rest.
A unitholder jokingly asked if the sale of MBC was being ‘forced’ onto MCT by its sponsor Mapletree. The Chairman reassured the unitholder that the acquisition is a case of a willing buyer and a willing seller. But he noted that the deal is a related party transaction which is why the management has gone through the procedure of obtaining independent valuations and the transaction scrutinized by its independent directors.
9. The proposed acquisition was voted through
The proposed acquisition of MBC was approved at the EGM with 95.51% of votes in favor of the resolution. MCT has since announced they plan to raise $529.1 million from the private placement and $515.2 million from the preferential offering.
Current unitholders are entitled to 17 new units for every 100 existing units at an issue price of $1.42 per unit. The issue price is an 8.4% discount to MCT’s last traded price of $1.55 (as at 1 August 2016). Unitholders can also apply for excess units. Books closure date is 3 August 2016 at 5:00 p.m.
2016年7月7日星期四
我的新Reits 組合
經過半年的摸索,終於動手將REITS加入我的投資組合裡。先試探式每隻買入多少,然後再按個別表現調整比重。還好入市時機不太差,暫時錄得+4%回報。REITS在英國公投脫歐後,還有逆市的上升,確是出人意外,這證明現在REITS也成了資金避難所!下一個階段,會考慮加入美國、日本和澳洲的REITS。


買入Frasers Centrepoint Trust (Singapore)
試探式買入新加坡的Frasers Centrepoint Trust@2.1(SGD),小試牛刀。買的原因是所有商場都不是位於市中心,卻在交通便捷的民生區。受經濟週期影響較少。且保持多年派息增長,yield有5.6%,也算不錯。現P/E=11.8,P/B=1.1,借貸率只28%,還有很大空間收購合適商場,提高回報率!
Frasers Centrepoint Trust 公司網站
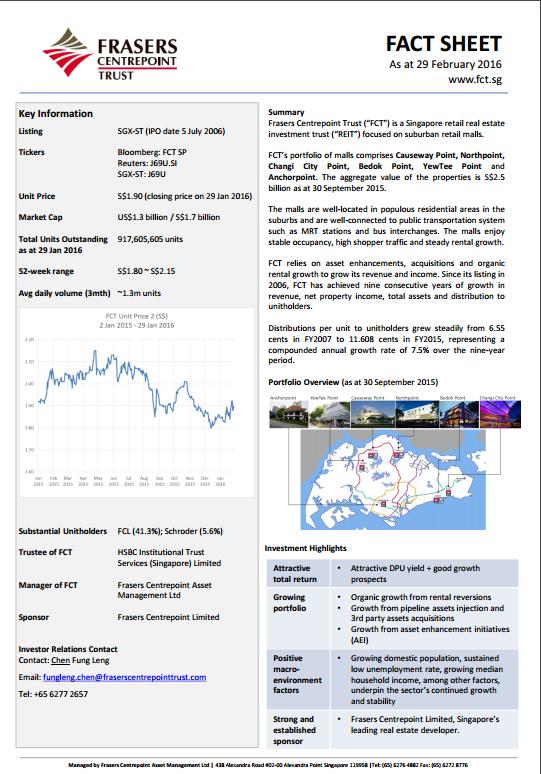

Frasers Centrepoint Trust 公司網站
2016年6月23日星期四
CapitaLand Mall Trust’s Annual Report: 11 Numbers Investors Should Know

By Hui Leong Chin - June 1, 2016
CapitaLand Mall Trust (SGX: C38U), an owner of multiple retail malls in Singapore, had released its latest 2015 annual report a few months back.
The annual report is a great place to learn more about the REIT. CapitaLand Mall Trust’s report contained a list of interesting numbers. Here are 11 numbers that may be worth knowing for investors:
At the end of 2015, CapitaLand Mall Trust had 16 properties and a whopping 3,086 leases. In comparison, its peer Frasers Centrepoint Trust (SGX: J69U), another REIT which owns retail malls in Singapore, had less than 700 tenant leases.
The annual shopper traffic to CapitaLand Mall Trust’s portfolio of malls is 348 million. This is impressive, given Singapore’s population of around 5.5 million people.
CapitaLand Mall Trust’s tenant retention rate was 81.1% in 2015. This suggests that the REIT has been able to maintain a strong relationship with its tenants.
The REIT also noted that no single tenant contributed more than 4.0% of its total gross rental income as at 31 December 2015. In fact, the 10 largest tenants accounted for under 20% of the REIT’s total gross rental income.
CapitaLand Mall Trust added that around 75% of its gross revenue caters to the necessity shopping segment. This may add resilience to the REIT’s portfolio during downturns.
The REIT’s loyalty programme, CAPITASTAR, boasts over 2.6 million members across five countries. There are more than 800,000 members in Singapore.
Moving on to debt, CapitaLand Mall Trust’s average term to maturity of its borrowings is 5.3 years. This is an increase compared to the 2.3 years to 4.7 years that were seen from 2011 to 2014. The REIT’s average cost of debt has also been relatively stable, hovering between 3.3% and 3.5%. In short, CapitaLand Mall Trust has been able to lengthen its debt term without incurring higher cost of debt.
A full 100% of CapitaLand Mall Trust’s debt is also unencumbered. Said another way, the REIT has not had to put up its assets as collateral when it borrows money. This is a major change from 2012, when only 50.4% of its debt was unencumbered.
訂閱:
文章 (Atom)